I am Harley West, Managing Director of Spotter Life and Spotter Finance. Over the last decade of working in the Australian financial sector, I have helped countless self-employed professionals protect their livelihoods.
A few weeks ago, I caught up for coffee with an independent cybersecurity consultant. He had just made the big jump from a secure corporate job to freelance consulting. He was buzzing about the freedom. He loved setting his own hours, choosing his projects, and securing better contract rates.
But as we mapped out his finances, a quiet fear surfaced. He shared a story about a former contractor colleague who had a nasty mountain biking accident. That colleague was off work for four months. Because he was an independent contractor, his income stopped the exact day he fell. He had zero sick leave and no paid recovery time. All he had was a mounting pile of software subscriptions, regular household bills, and a mortgage that still needed paying.
Calculate Your Exposure Risk
Discover how long your savings will last if your freelance contract income stops today.
The Hidden Trap of Independent Consulting
When you leave an employer, you leave behind the safety net. In the consulting world, your ability to wake up, sit at your desk, and execute your work is your most valuable asset. Over your career, you will earn a significant amount of money. But if a health shock takes you out of action, those hard-earned savings can drain away in a matter of months.
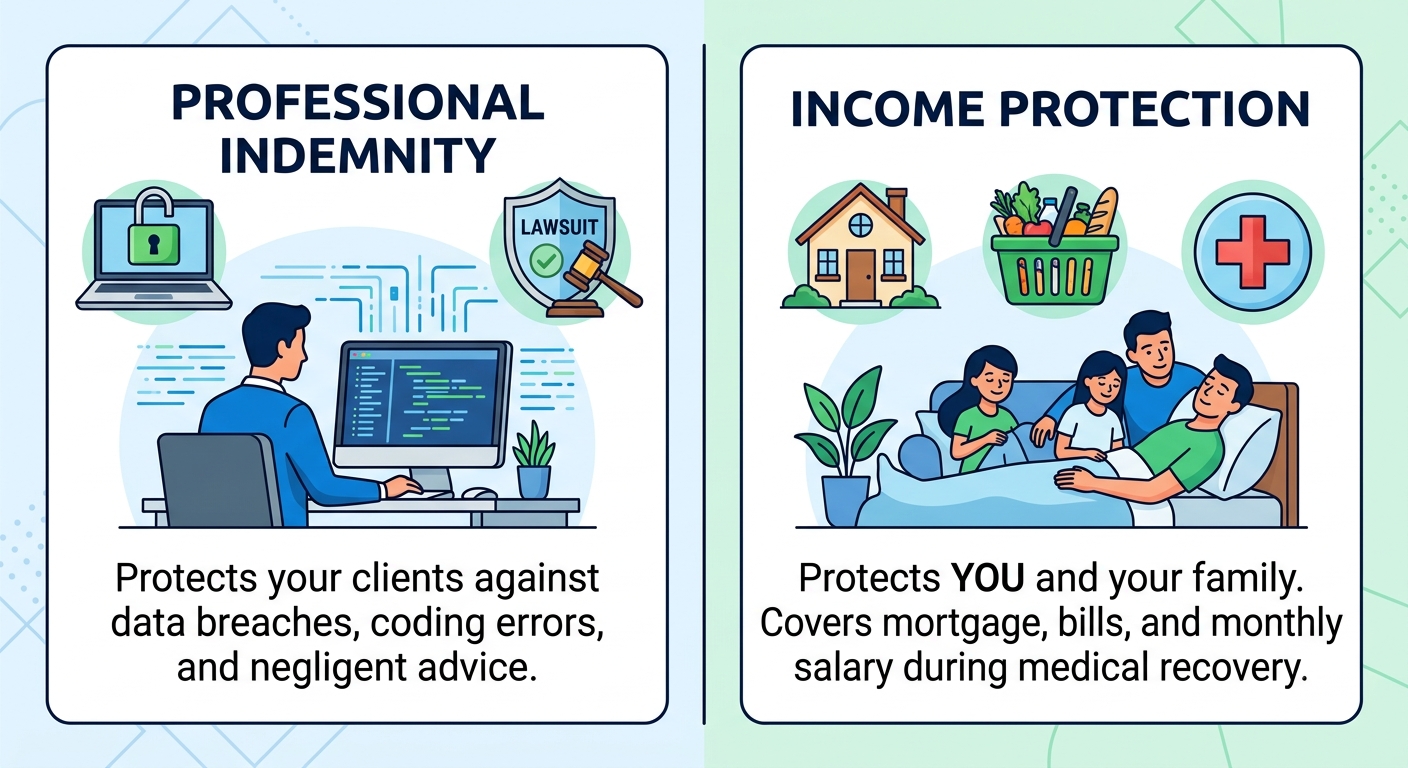
Many IT consultants tell me they feel secure because they have professional indemnity insurance. In the tech sector, this is often a strict contract requirement. But here is the hard truth. Professional indemnity protects your clients if you make a mistake or face a data breach. It will not buy your groceries or pay your power bill if you end up in a hospital bed.
To keep your household running while you recover, you need a different approach.
Building a Safety Net That Fits Your Life
This is where tailored income protection comes in. It pays a monthly benefit of up to 75% of your pre-tax salary if a severe illness or injury stops you from working.
Instead of just selling a generic product, we look at how to build a safety net that fits your real life. Here is how we structured his cover to give him peace of mind without stretching his budget:
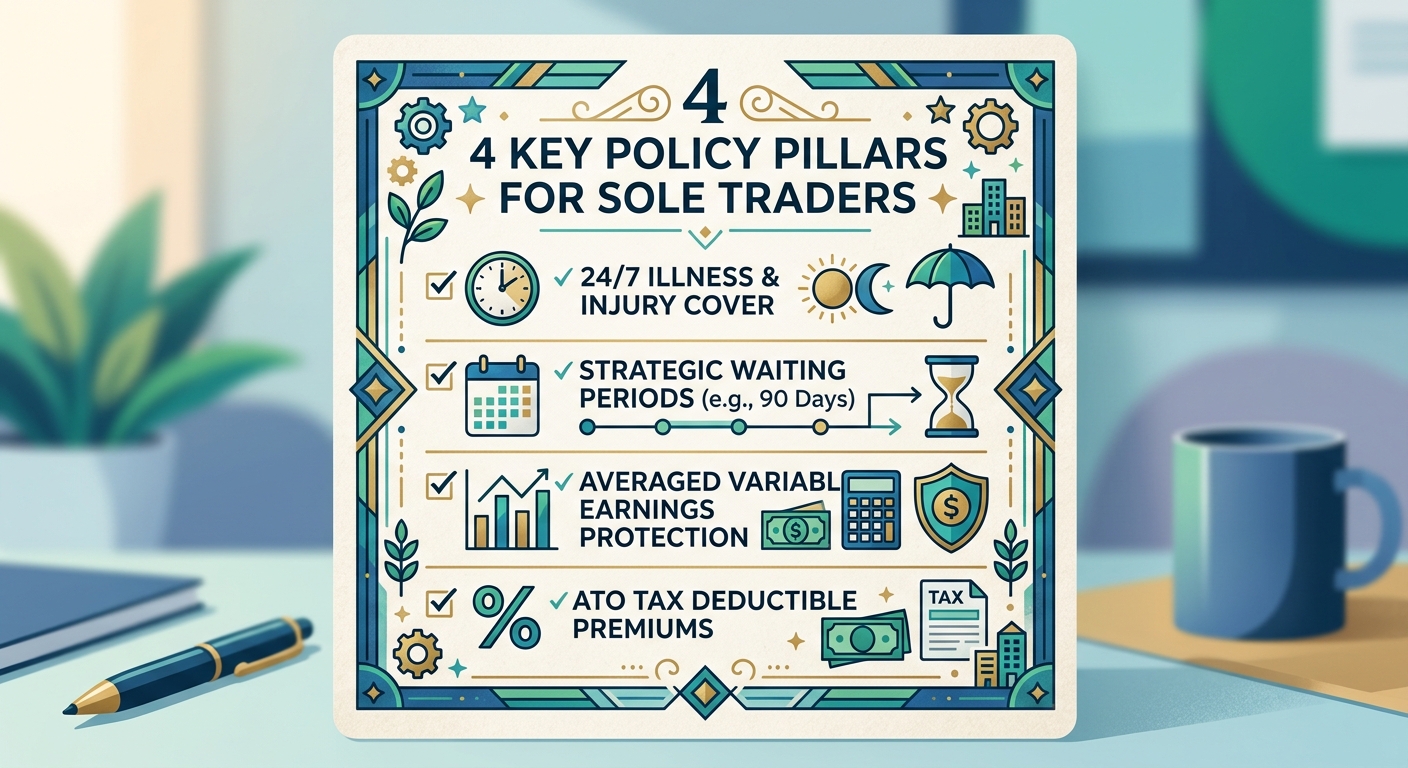
- Round the Clock Cover: We made sure he was protected 24 hours a day. Whether he was dealing with a serious long-term illness or just injured his knee playing weekend sports, his policy would step in.
- Smart Waiting Periods: Because he had a good buffer of savings built up, we set a 90-day waiting period. This meant his ongoing premiums were much cheaper, but he still had a solid backup plan if a long-term disaster struck.
- Managing Variable Income: Freelance income goes up and down. A good setup averages out your fluctuating earnings so there are no nasty surprises if you ever need to claim.
- Tax Benefits: Under Australian Taxation Office (ATO) guidelines, premiums paid for policies designed to replace lost salary or wages are generally tax-deductible if you pay for them personally out of your own pocket. This makes securing your livelihood much more affordable.
Smarter Protection, Made Easy
At Spotter Life, we exist to make choosing insurance simple, accessible, and cost-effective. You should not have to spend your weekends reading confusing policy documents. You deserve clear advice that actually makes sense and gives you confidence.
We can review your current setup to ensure your safety net holds strong when you need it most.
Compliance & General Advice Notice: Spotter Finance Pty Ltd (ABN 34 617 912 053) Australian Financial Services Licensee Number (540383) is authorised to provide general advice in superannuation and life insurance products only. Any information or advice contained on this website is general in nature and has been prepared without taking into account your objectives, financial situation or needs. Before acting on any information or advice on this website, you should consider the appropriateness of it (and any relevant product) having regard to your circumstances and, if a current offer document is available, read the offer document before acquiring products named on this website. Please note our advice does not include independent financial, legal and taxation advice prior to acquiring a product.
How do you currently manage your financial reserves to cover unexpected gaps between your contract billing cycles?