
If you have held a life insurance policy for a few years, you might be well acquainted with a frustrating annual routine. You open your renewal notice, read the summary, and discover that your premiums have jumped yet again. For many older Australians, this annual price hike goes beyond a minor annoyance. It turns into genuine bill shock.
At Spotter Life, our team sees this happen all the time. It is one of the most common issues we help clients navigate. Families are often forced to reduce or cancel their coverage precisely at the stage of life when they might need it the most.
Let us look at a common scenario. Consider a hypothetical client named Peter. Peter took out a standard life insurance policy when he was 35 to protect his young family and cover his new mortgage. For the first decade, the cost was barely a blip in his monthly budget.
However, as Peter approached his late 50s, those minor annual increases compounded. Suddenly, he was paying thousands of dollars a year, and the policy he bought to provide peace of mind had become a major financial stressor.
The primary reason behind these rising costs usually comes down to how your policy is structured from the beginning. Understanding the difference between stepped vs level premiums Australia is a highly effective financial strategy you can use to protect your long-term wealth and ensure your coverage remains affordable well into retirement.
Below is a clear, straightforward breakdown of how these premium structures work, the long-term cost analysis of both options, and how you can stop your life cover from becoming too expensive.
The Root of the Problem: Life Insurance Premium Types
When you first apply for a life insurance policy, the quote you receive is based on a specific premium structure. In Australia, the two primary life insurance premium types are stepped premiums and level premiums.
The structure you choose dictates how your insurer will calculate your ongoing costs year after year. Making the wrong choice early on, or failing to restructure your policy as your needs change, can end up costing you thousands of dollars over the lifetime of your policy.
What Are Stepped Premiums?
Stepped premiums are the default option for most new life insurance policies. This is largely because they look very appealing on day one.
With a stepped premium, your insurance cost is recalculated every single year based on your current age. Because younger people are statistically less likely to make a claim on life, trauma, or Total and Permanent Disability (TPD) insurance, the premiums start off quite cheap.
However, as you get older, the statistical risk of illness, injury, or death naturally increases. Consequently, your premiums step up every year upon renewal.
- In your 30s: The annual increases are usually marginal and barely noticeable.
- In your 40s: The increases start to become more pronounced.
- In your 50s and 60s: The curve steepens sharply, often doubling or tripling in cost over a short period.
This structure creates a scenario where an older Australian on a fixed income is suddenly hit with thousands of dollars in annual premium costs. Ultimately, it makes the policy financially unsustainable for many people.
What is Level Premium Life Insurance?
If you want to avoid the aggressive price hikes associated with getting older, level premium life insurance is the alternative strategy.
Instead of recalculating your cost based on your current age every year, a level premium effectively averages out the cost of your insurance over the long term. Your premium is calculated based on your age at the time you take out the policy. It then remains relatively stable over time.
Important Note: The word “level” does not mean the price will never change under any circumstances. Level premiums can still increase slightly due to inflation, often tied to CPI adjustments, or if the insurer universally raises rates for all customers across their portfolio. However, your premium will not increase simply because you have had a birthday.
Financial Strategy: The Long-Term ROI Analysis
To understand the return on investment of restructuring your policy, we need to look at the mathematical crossover point between these two premium types.
When you first request a quote for a level premium policy, you will notice it is more expensive than a stepped premium policy. You are effectively paying a bit more upfront to subsidise the cost of your insurance in your later years.
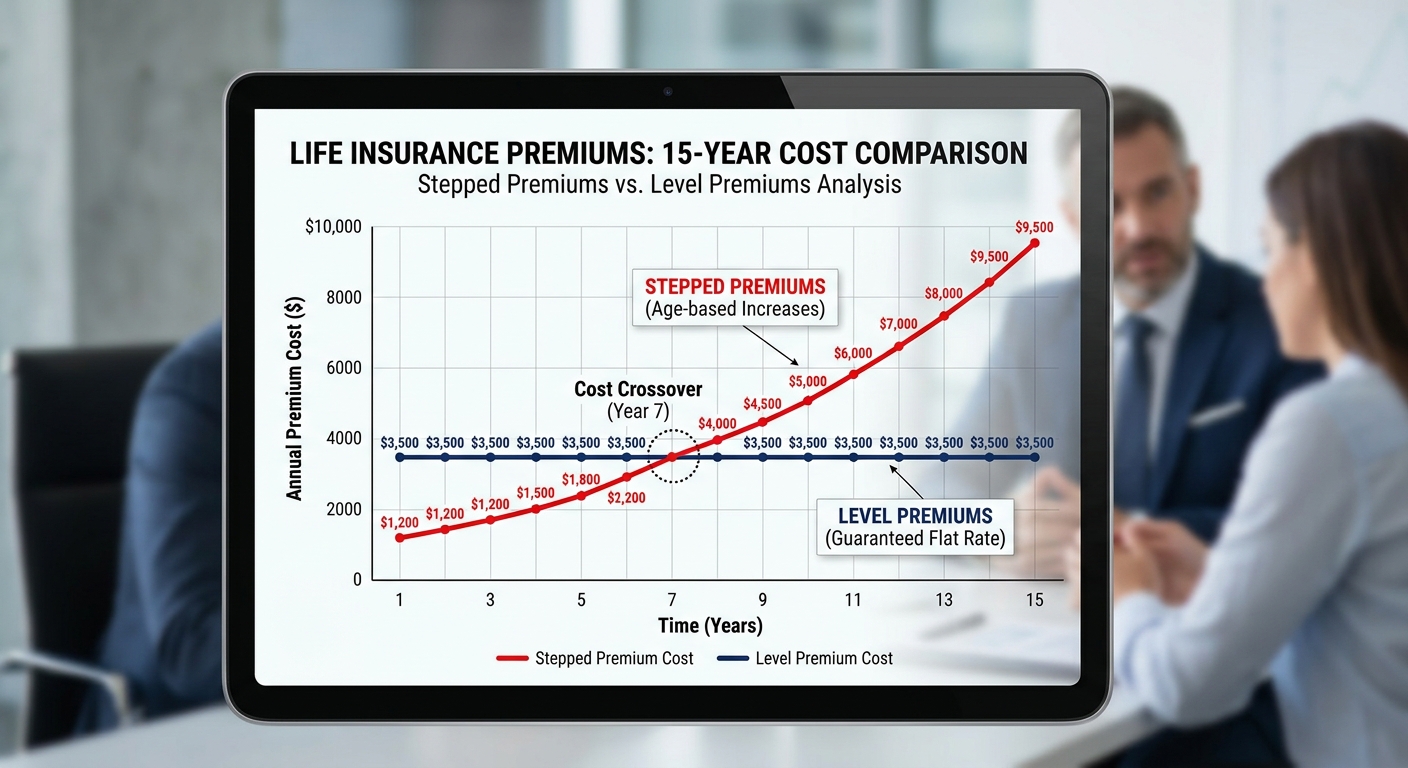
The Crossover Point
Typically, if you hold a policy for 10 to 15 years, you will reach a crossover point. This is the year where the rapidly rising stepped premium finally overtakes the steady level premium.
| Timeline | Financial Impact |
|---|---|
| Years 1 to 10 | You pay more for the level premium than you would have for the stepped premium. |
| Years 10 to 15 | The stepped premium catches up to the level premium. |
| Years 15+ | The stepped premium rises sharply, while the level premium stays steady. During your 50s and 60s, the level premium generates significant annual savings, which heavily outweigh the extra money you paid in the early years. |
For older Australians who plan to hold their life insurance into retirement, switching to a level premium structure earlier in life is a strategic move to prevent future bill shock. If you are already older, restructuring an existing policy now to lock in your current age rate can still be a smart way to stabilise your expenses.
Which Premium Structure is Right for You?
Choosing between these two structures comes down to your financial goals and how long you intend to hold the policy.
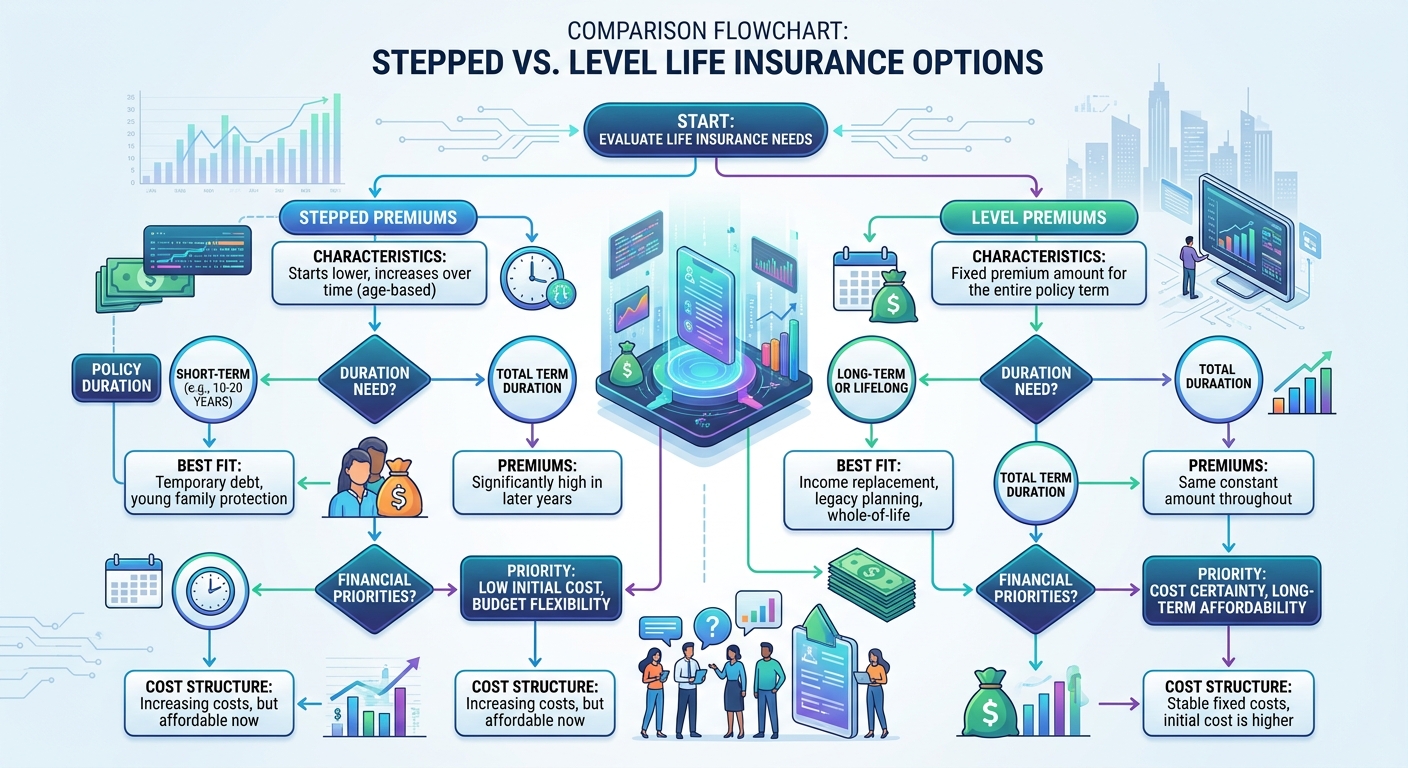
You should consider Stepped Premiums if:
- You only need coverage for a short period, such as 5 to 10 years, to cover a specific debt like a new mortgage.
- You are currently on a tight budget and need the absolute cheapest coverage available today, with the plan to review it later.
- You anticipate needing to reduce your level of cover in the near future, perhaps because you are downsizing a home or your children are becoming financially independent.
You should consider Level Premium Life Insurance if:
- You plan to hold your policy for the long term, usually 10 years or more.
- You want predictable, stable expenses that you can easily budget for over time.
- You want to maintain a high level of coverage into your 50s and 60s without being priced out of your policy.
- You want peace of mind knowing your insurance will not become an unmanageable financial burden right when your health risks are highest.
Stop The Bill Shock: Restructure Your Policy with Spotter Life
At Spotter Life, we believe securing life insurance should be straightforward, transparent, and designed around your specific circumstances. If you are currently experiencing bill shock from an existing stepped policy, you do not have to simply accept the price hikes. You also do not have to cancel your hard-earned coverage.
Our team of insurance experts can help you conduct a cost analysis to see if restructuring your policy into a level premium makes financial sense for your future. We take the hassle out of the insurance comparison process.
Why Choose Spotter Life?
- Trusted Expertise: We have been trusted by thousands of Australians since 2017.
- Broad Comparison: We partner with nine of Australia’s most trusted retail insurers, including TAL, AIA, and Zurich. This gives you one of the broadest ranges of insurers to compare at competitive rates.
- Major Savings: By comparing the market, we can help you save up to 30% based on a typical policy.
- Free Service: Our service is 100% free for Spotter Life customers. You can get a market comparison in minutes with absolutely no pressure to buy.
Do not let rising premiums force you out of the protection you deserve.
Contact Us Today for a Free Policy Review
Take control of your life insurance costs today. You can compare personal insurance options over the phone or online with no paperwork and no hassle.
Call Us: 1300 793 143
Get a quick quote online: Fill out our form, and we will help you navigate your options, save time and money, and ensure you get comprehensive coverage at competitive rates.
Disclaimer:
Spotter Finance Pty Ltd (ABN 34 617 912 053) Australian Financial Services Licensee Number (540383) is authorised to provide general advice in superannuation and life insurance products only. Any information or advice contained on this website is general in nature and has been prepared without taking into account your objectives, financial situation or needs. Before acting on any information or advice on this website, you should consider the appropriateness of it (and any relevant product) having regard to your circumstances and, if a current offer document is available, read the offer document before acquiring products named on this website. Please note our advice does not include independent financial, legal and taxation advice prior to acquiring a product.